TL;DR

Get the little things that make your day delivered free with Prime
- Fast, free delivery on millions of items
- Prime Video, Amazon Music and more included
- Member-only deals all year
A LifeHack report cautions that selling a home and moving to a smaller one may cost enough to erase years of housing savings. It recommends estimating the full cost of the move and dividing it by realistic annual savings before deciding; the outcome depends on each household’s figures and needs.
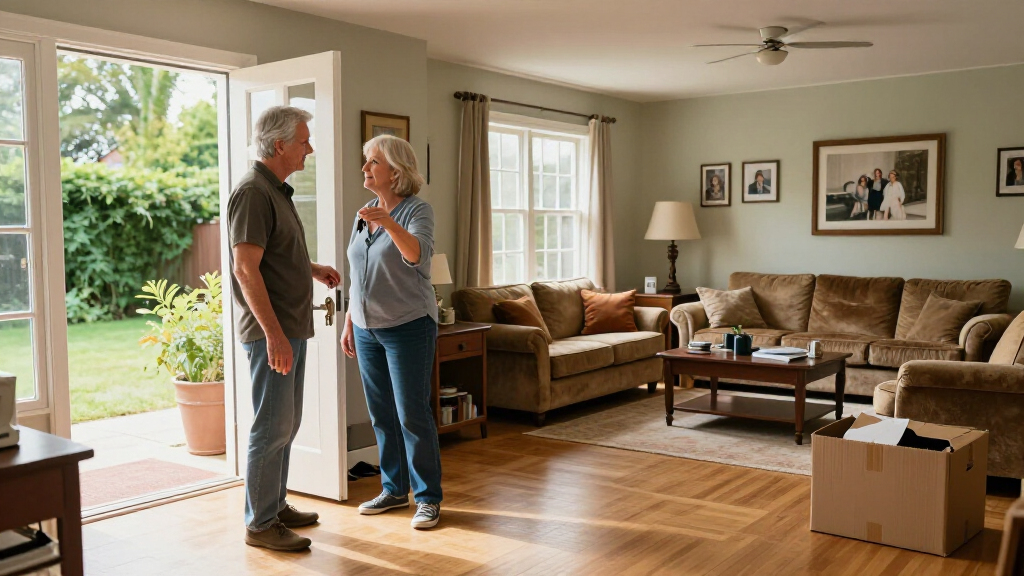
A LifeHack report on retirement downsizing argues that selling a home and buying a smaller one can be a costly move rather than an automatic way to improve retirement finances. It advises homeowners to calculate the one-time cost of selling, buying and moving against realistic yearly savings before listing a property, because the break-even point may take years.
The report frames downsizing as a spending decision with a payback period. Its basic calculation is to total the costs incurred once, estimate how much the new home will save each year, and divide the first figure by the second. The result estimates how many years it would take for the savings to cover the move. It does not establish a universal break-even point: sale price, purchase price, fees, moving distance and future housing costs differ by household.
To illustrate the scale of the transaction, the report cites Freddie Mac guidance that seller fees and taxes can run 2% to 4% of the sale price, in addition to agent commission, which its guidance gives as a broad 3% to 8% range. Freddie Mac puts typical buyer closing costs at 2% to 5% of the purchase price. These are planning ranges, not quotes. The report also cites Move.org estimates of about $7,600 for a full-service local move under 100 miles and $9,140 or more for a longer move.
Using a $450,000 sale and a $300,000 purchase as an example, the report estimates transaction costs of roughly $28,500 to $69,000, before the moving bill and expenses such as repairs or furnishings. The actual total depends on specific contracts and circumstances. The report says commissions are negotiable and advises readers to use the compensation terms in their own agreements rather than assume a standard rate.
When Moving Costs Outlast Savings
The financial stakes are meaningful because a homeowner may have substantial equity but still receive much less cash from a sale than the difference between the two homes’ prices suggests. Closing costs, commissions, moving expenses and setup costs can consume part of that gap. If the smaller home only trims monthly expenses modestly, a household may need to stay there for many years before the move produces net savings.
The report also stresses that a home provides more than a balance-sheet value. Proximity to family, familiar services and the ability to remain in a community can affect whether a move works for an individual. These factors cannot be reduced to the break-even calculation, but they belong in the decision alongside cash flow, accessibility and upkeep. The report’s argument is not that retirees should stay or go; it is that the choice should be based on both the numbers and the homeowner’s circumstances.
Products Worth Considering

Blueair Blue Pure 511i Max Air Purifier for Home and Bedroom

Samsung 42-Inch Class OLED S90F 4K Smart TV (2025)

Samsung 48-Inch S90H OLED 4K Smart TV (2026)
As an affiliate, we earn on qualifying purchases.
Costs Behind the Sale Price
The report cites AARP’s 2024 Home and Community Preferences survey, which found that 75% of adults aged 50 and older said they wanted to live in their current home for as long as possible. That finding records a stated preference, not the share who will be able to stay or a recommendation for every household. It provides context for why general pressure to downsize may not match what many older adults want.
Mortgage status can also shape the calculation. The report cites Harvard’s Joint Center for Housing Studies, which said that in 2022, 41% of homeowners aged 65 to 79 had a mortgage; among homeowners aged 80 and older, 31% did. Those figures mean many homeowners in both age groups had no mortgage, though they still faced costs such as property taxes, insurance, utilities and maintenance. A smaller home may reduce some expenses, but the report warns that savings can be limited or offset by fees, including a condominium association charge.
Buyer-agent compensation also depends on the particular arrangement. The report notes that National Association of Realtors practice changes took effect in August 2024. Under those changes, covered listing services may not display offers of buyer-agent compensation, and buyers working with an agent generally sign a written agreement setting that compensation before touring homes. Sellers may still agree to cover some or all of it.
“Moving costs money now and saves money later, which makes it an investment with a payback period rather than a way to free up cash.”
— LifeHack report
The Household Numbers Still Matter
The figures cited are broad estimates and historical survey or housing data, not a forecast of what a specific homeowner will pay or save. Actual transaction costs depend on the home, location, agreements and move. Future savings depend on the replacement property’s taxes, insurance, utilities, maintenance and any association fees, as well as how long the owner remains there.
The report’s example does not include a complete budget for every possible expense, and it cannot determine whether downsizing is suitable for a particular person. It also does not quantify the personal value of staying near family, services or an established support network. Those considerations, along with health, accessibility and available housing choices, remain specific to each household.
Price the Move Before Listing
The report recommends collecting estimates for the sale, purchase and move, then comparing them with a realistic annual savings figure for a specific replacement home. Homeowners can use the resulting break-even estimate to ask whether they expect to stay long enough for the savings to offset the initial costs. Brokerage terms, closing costs and moving quotes should be checked against actual written estimates rather than broad national ranges.
The next step is a household decision, not a predetermined sale: compare the financial estimate with maintenance needs, accessibility, monthly affordability and the value of remaining in the current community. The report offers no single outcome for retirees, and a move’s financial result will only become clearer once a homeowner has prices for both the existing home and a realistic alternative.
Key Questions
How can I estimate whether downsizing will pay off?
Add the one-time costs of selling, buying and moving, including likely setup expenses. Divide that amount by the estimated annual savings from the new home to calculate an approximate break-even period. Use household-specific figures where possible.
What costs should be included?
Account for seller fees and taxes, agent compensation, buyer closing costs, movers and likely repairs or replacement furnishings. Compare recurring costs too, including property taxes, insurance, utilities, maintenance and association fees.
Are the cost ranges in the report guaranteed?
No. The cited figures from Freddie Mac and Move.org are broad planning estimates. Actual costs vary with the property, location, contract terms, move distance and other details.
Does the report say retirees should not downsize?
No. It argues that downsizing can make sense for some people, but should not be treated as an automatic financial win. The decision depends on individual costs, likely savings, personal needs and how long the homeowner expects to stay.
Source: rss